🧃Needs
A need is a good or service that is essential for living.
Examples:
- Food
- Clean water
- Clothing
- Shelter
This chapter explains why businesses exist, how scarce resources create choices, and how firms combine land, labour, capital and enterprise to produce goods and services. It also covers opportunity cost, specialisation, division of labour and added value.
Start here: students learn the basic economic ideas that explain why businesses exist and why choices must be made.
A need is a good or service that is essential for living.
A want is a good or service that people would like to have but which is not essential for living.
The economic problem exists because:
There are not enough resources available to produce all the goods and services that everyone wants.
Simply increasing the amount of money in an economy does not solve the economic problem because printing more money does not automatically create more goods and services.
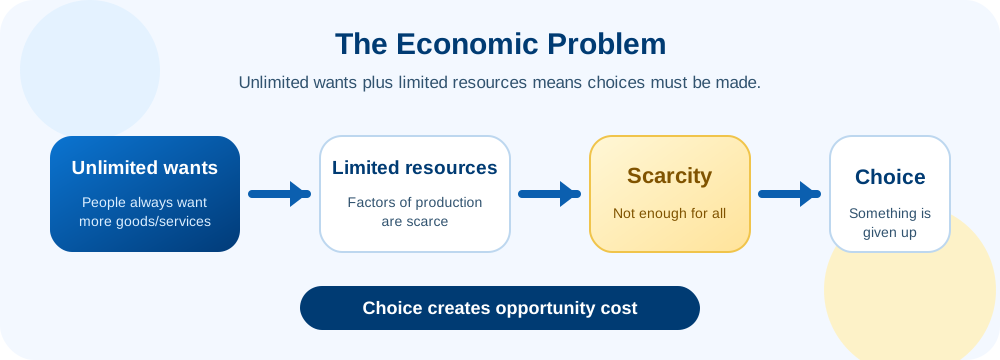
Scarcity means there are insufficient products and resources to satisfy all the wants of the population.
Because resources are scarce, individuals, businesses and governments have to make choices.
Factors of production are the resources needed to produce goods and services.
There are four factors of production:
| Factor | Meaning | Examples |
|---|---|---|
| Land | Natural resources provided by nature | Land, forests, oil, gas, minerals |
| Labour | People available to produce goods and services | Factory workers, teachers, shop workers |
| Capital | Finance, machinery and equipment used in production | Machinery, equipment, money invested |
| Enterprise | Skill and risk-taking ability used to organise the other factors of production | Entrepreneur/business owner |
Opportunity cost is:
Because resources are limited, choosing one option normally means giving up another.
A person has enough money for either a holiday or a new car.
If the person chooses the holiday, the car is the opportunity cost.
A business can afford either Machine A or Machine B.
If it chooses Machine A, Machine B is the opportunity cost.
The government can build either a new school or a new road.
If it builds the road, the school is the opportunity cost.
This topic explains how work can be organised to improve efficiency, and also why specialisation can create problems.
Specialisation occurs when people or businesses concentrate on the activities that they are best at.
Specialisation has become increasingly common because:
Division of labour occurs when the production process is divided into separate tasks and each worker specialises in one task.
For example, in a furniture factory:
Division of labour is therefore a form of specialisation.
Workers repeatedly performing the same task become skilled at it.
Result: output can increase.
Workers do not continually move between different jobs or workstations.
Result: production can become faster.
Workers only need to be trained for a limited number of tasks.
Result: training can be quicker and cheaper.
Repeating the same task can become monotonous.
Result: motivation and efficiency may fall.
If a specialised worker is absent and nobody else can perform the task, production may be disrupted or stopped.
Do not just state:
“Division of labour increases efficiency.”
Develop the answer:
Workers become highly skilled at one particular task, allowing them to complete it more quickly. This can increase the firm's output and potentially reduce production costs.
This topic links factors of production to the goods and services businesses produce for customers.
Businesses exist to combine factors of production to produce goods and services that satisfy people's wants.
Physical products that can be seen and touched.
Activities provided to customers rather than physical products.
Businesses can differ considerably. They may be:
However, all businesses combine factors of production to produce goods or services.
Business activity also:
This topic explains how businesses create value, calculate added value, and understand why added value is not the same as profit.
Added value is one of the most important ideas in this chapter.
It is the difference between what a business sells a product for and the cost of the materials/components bought from other businesses.
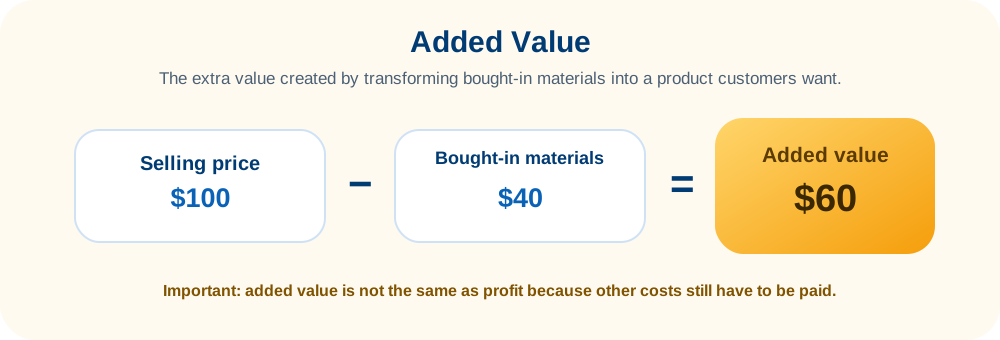
The business still has to pay other costs from the added value, such as:
The book illustrates this with a house sold for $100,000 where bought-in materials cost $15,000. The $85,000 difference is added value, but it is not all profit because other costs still have to be paid.
A business needs to add value so that it can:
For example:
If the added value is greater than the other costs of operating the business, the business may make a profit.
There are two main methods.
A business may persuade customers to pay more by creating a higher-quality image.
Possible methods include:
A business could:
A bakery spends $0.30 on the flour, sugar and butter used to make a cake.
Selling price = $1.00
If customers are willing to pay $1.50 because the cake is served at a table:
Use this final topic to memorise key definitions and check the skills needed for examination questions.
| Term | Exam-ready meaning |
|---|---|
| Need | A good or service essential for living |
| Want | A good or service people would like to have but which is not essential |
| Economic problem | Unlimited wants but limited resources, creating scarcity |
| Factors of production | Resources required to produce goods and services |
| Scarcity | Insufficient resources/products to satisfy all wants |
| Opportunity cost | The next best alternative given up when making a choice |
| Specialisation | People or businesses concentrating on what they are best at |
| Division of labour | Dividing production into separate tasks, with workers specialising in particular tasks |
| Business | An organisation that combines factors of production to produce goods and services that satisfy wants |
| Added value | Selling price minus the cost of bought-in materials and components |
By the end of Chapter 1, students should be able to:
These areas correspond closely to the chapter's own revision checklist and exam-style coverage.