Business Finance: Needs and Sources
This chapter explains why businesses need finance, how finance is classified, and how managers choose the most suitable source of finance for different business situations.
Topic 1: Why Businesses Need Finance
Finance is needed before a business starts, while it operates, and when it wants to grow.
1. Role of the Finance Department
The Finance department is responsible for:
- recording financial transactions
- preparing accounts
- providing financial information to managers
- forecasting cash flows
- helping to make financial decisions, including choosing sources of finance.
2. Why Businesses Need Finance
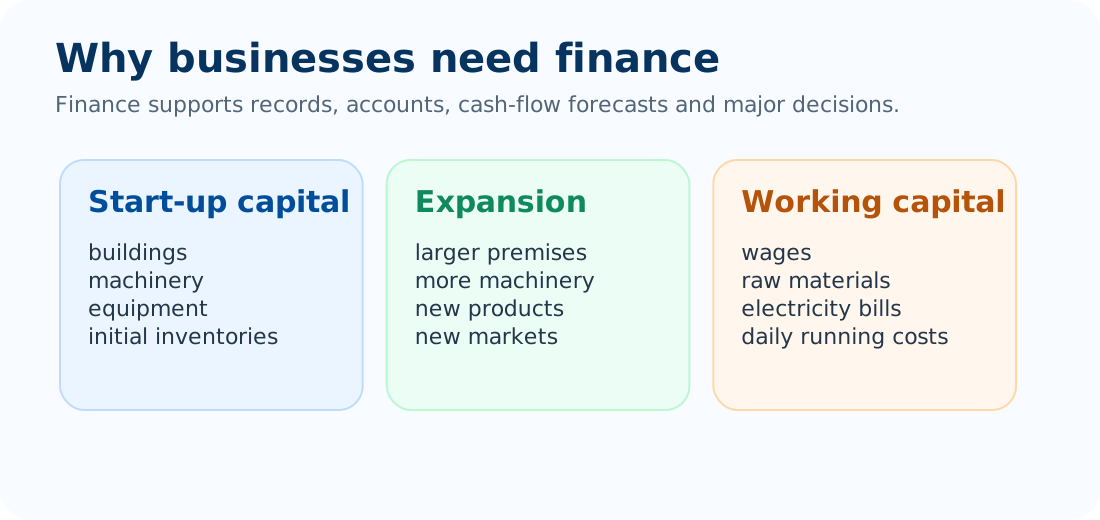
There are three main reasons why businesses need finance.
1. Start-up Capital
Money is needed to start a new business. It may be used to buy buildings, machinery, equipment and initial inventories.
Start-up capital is the finance needed before a new business can begin trading.
2. Business Expansion
An existing business may need finance to buy larger premises, buy more machinery, develop new products, enter new markets or take over another business.
3. Additional Working Capital
Working capital is the finance needed to pay day-to-day costs such as wages, raw materials and electricity bills.
A profitable business can still fail if it does not have enough working capital to pay its bills.
3. Capital Expenditure and Revenue Expenditure
| Type | Meaning | Examples | Easy Difference |
|---|---|---|---|
| Capital expenditure | Money spent on non-current assets that will last for more than one year. | Buildings, machinery, vehicles. | Long-term assets. |
| Revenue expenditure | Money spent on the day-to-day running of the business. | Wages, rent, electricity. | Everyday expenses. |
Topic 2: Internal and External Sources of Finance
Sources of finance can be classified by where the money comes from and by how long it is needed.
4. Sources of Finance
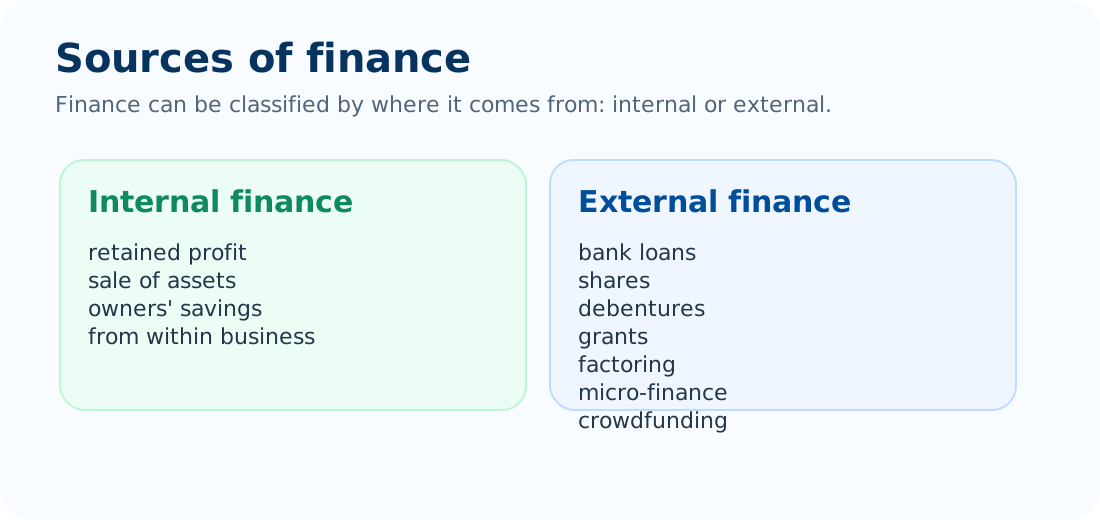
Sources of finance can be classified in two main ways:
Internal finance and external finance.
Short-term finance and long-term finance.
5. Internal Finance
The most important internal sources are retained profit, sale of existing assets and owners' savings.
6. Retained Profit
Retained profit is profit kept in the business rather than paid out to the owners.
Advantages
- Does not have to be repaid.
- No interest has to be paid.
Disadvantages
- A new business will not have retained profit.
- The amount available may be too small.
- Owners or shareholders receive less profit/dividend.
Suitable for: a profitable existing business financing expansion.
7. Sale of Existing Assets
A business may sell assets it no longer needs, such as unused buildings or old equipment.
Advantages
- Raises finance without borrowing.
- Does not increase business debt.
Disadvantages
- It may take time to find a buyer.
- The amount raised is uncertain.
- New businesses usually do not have spare assets to sell.
8. Owners' Savings
Sole traders and partners may invest their own savings in the business.
Advantages
- Usually available quickly.
- No interest needs to be paid.
Disadvantages
- Savings may be insufficient.
- The owner’s personal financial risk increases.
9. External Finance
Important external sources include bank loans, shares, debentures, grants, factoring, micro-finance and crowdfunding.
10. Bank Loan
A bank loan is money borrowed from a bank that must be repaid, usually with interest.
Advantages
- Can provide a large amount of finance.
- Can be arranged for different periods of time.
- The owners do not lose ownership of the business.
Disadvantages
- Interest must be paid.
- The loan must be repaid.
- The bank may require security/collateral.
Suitable for: buying expensive long-term assets or financing expansion.
11. Issue of Shares
Limited companies can raise finance by selling shares.
Advantages
- Finance does not have to be repaid.
- No interest payments.
Disadvantages
- Shareholders normally expect dividends.
- Existing owners may lose some control of the company.
12. Debentures
Debentures are long-term loan certificates issued by limited companies. They can provide finance for many years.
Disadvantage
- Interest must be paid.
- The money must eventually be repaid.
13. Government Grants and Subsidies
Governments or other organisations may provide finance to businesses.
Advantage
- The money usually does not need to be repaid.
Disadvantage
- Conditions may be attached. For example, a business may have to locate in an area with high unemployment.
14. Factoring of Debts
A business may sell the money owed by customers to a specialist debt factor. The factor gives immediate cash but pays less than the full value of the debt.
Advantages
- Provides cash quickly.
- The factor takes responsibility for collecting the debt.
Disadvantage
- The business does not receive the full amount owed by customers.
15. Micro-finance
Micro-finance provides small loans and other financial services to people who may not be able to obtain finance from traditional banks.
It is particularly useful for small entrepreneurs, low-income individuals and businesses without assets to offer as security.
Traditional banks may refuse these borrowers because the loan required is very small or because they have little or no collateral.
16. Crowdfunding
Crowdfunding raises finance by obtaining relatively small amounts of money from a large number of people, usually through the internet.
Advantages
- Can raise substantial finance quickly.
- Useful when traditional sources are unavailable.
- Helps test public interest in the business idea.
Disadvantages
- The campaign may fail to raise the required amount.
- Publicising the idea may allow competitors to copy it.
- Successful campaigns often require strong publicity.
Topic 3: Short-Term and Long-Term Finance
The length of time finance is needed should match the purpose of the finance.
17. Short-Term Finance
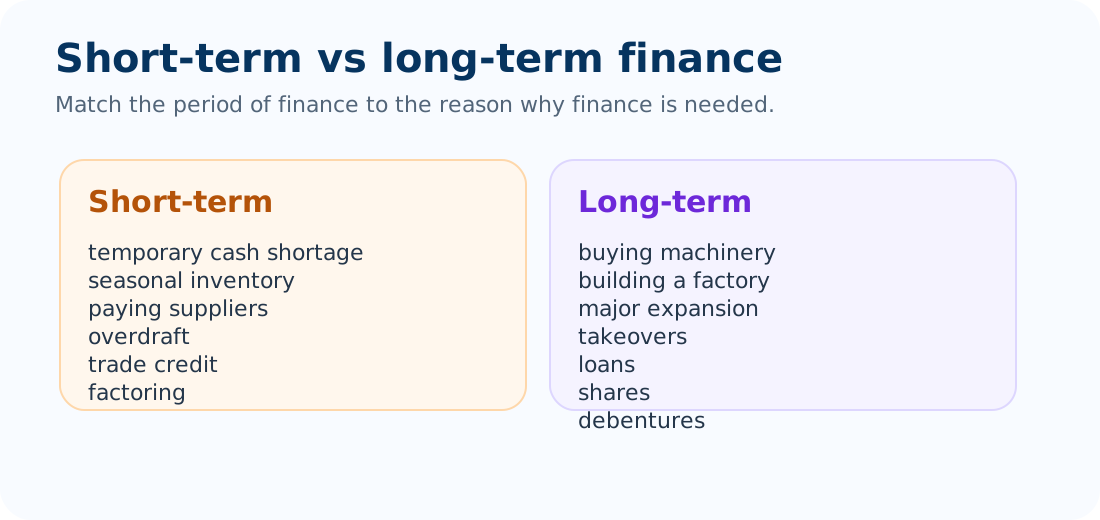
Short-term finance is mainly used to solve temporary cash shortages and provide working capital.
Three important sources are overdraft, trade credit and factoring.
18. Bank Overdraft
An overdraft allows a business to spend more money than it currently has in its bank account, up to an agreed limit.
Advantages
- Flexible.
- Interest is paid only on the amount overdrawn.
- Useful for temporary cash shortages.
Disadvantages
- Interest rates may change.
- The bank can demand repayment at short notice.
Suitable for: short-term problems such as paying wages while waiting for customers to pay.
19. Trade Credit
Trade credit occurs when suppliers allow a business to buy goods now and pay later.
Advantage
- It is effectively an interest-free source of short-term finance.
Disadvantage
- Paying suppliers too slowly may damage relationships.
- Discounts may be withdrawn.
- Suppliers may refuse future orders.
20. Long-Term Finance
Long-term finance is finance available for more than one year. It is normally used for:
- purchasing non-current assets
- business expansion
- takeovers.
Important sources include bank loans, hire purchase, leasing, shares and debentures.
21. Hire Purchase
Hire purchase allows a business to purchase an asset by making payments over a period of time.
Advantage
- The business does not need the full purchase price immediately.
Disadvantages
- A deposit is normally required.
- Interest can make the total cost high.
22. Leasing
Leasing allows a business to use an asset without buying it. The business makes regular payments to the leasing company.
Advantages
- No large initial purchase payment.
- Maintenance may be carried out by the leasing company.
Disadvantage
- Over time, leasing may cost more than buying the asset.
23. Short-Term vs Long-Term Finance
| Need | Suitable Type |
|---|---|
| Temporary cash shortage | Short term |
| Seasonal increase in inventory | Short term |
| Paying suppliers | Short term |
| Buying machinery | Long term |
| Building a factory | Long term |
| Business takeover | Long term |
| Major expansion | Long term |
A long-term asset should normally be financed using a long-term source, while a temporary working-capital problem should normally use a short-term source.
Topic 4: Choosing the Most Suitable Source of Finance
In examination questions, students must apply the source of finance to the business situation.
24. Choosing the Most Suitable Source of Finance
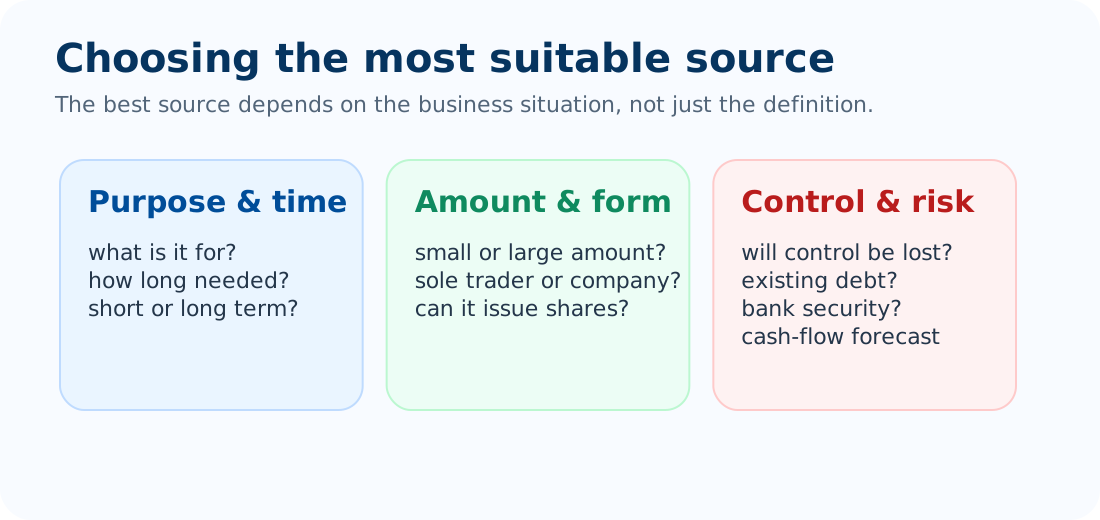
The business should consider five important factors:
- Purpose and time period: What is the money needed for and for how long?
- Amount required: A small amount may be financed through an overdraft or retained profit, while millions may require shares or long-term borrowing.
- Legal form and size: A sole trader cannot issue shares. A large public limited company has many more financing options.
- Control: Selling shares may reduce the existing owners’ control of the company.
- Existing debt / risk: A business that already has large loans may find further borrowing risky.
25. Gearing
A business with a high proportion of loan finance is highly geared.
High gearing can be risky because:
- interest must be paid even when profits are low
- the business still has to repay the loans
- banks may be unwilling to provide further loans.
26. Will a Bank Provide a Loan?
Banks may consider:
- the business’s cash-flow forecast
- expected future profits
- existing loans
- whether collateral/security is available
- the business plan.
27. Choosing Finance in an Exam
There is no source of finance that is always best. Students need to apply the source to the business.
Topic 5: Key Definitions and Exam Checklist
Use these key terms and checklist points for final revision.
Key Definitions
| Term | Meaning |
|---|---|
| Start-up capital | Finance needed before a new business begins trading. |
| Working capital | Finance needed to pay day-to-day costs. |
| Capital expenditure | Spending on non-current assets lasting more than one year. |
| Revenue expenditure | Spending on day-to-day business expenses. |
| Internal finance | Finance obtained from within the business. |
| External finance | Finance obtained from outside the business. |
| Overdraft | Permission to spend more than the amount currently in a bank account. |
| Trade credit | Buying from suppliers now and paying later. |
| Micro-finance | Small loans and financial services for people not normally served by traditional banks. |
| Crowdfunding | Raising small amounts from many people, usually through the internet. |
| Gearing | Proportion of capital financed through long-term borrowing. |
What Students Must Know for the Examination
Students should be able to:
- explain the three main reasons businesses need finance
- distinguish between capital and revenue expenditure
- distinguish between internal and external finance
- explain the main advantages and disadvantages of retained profit, owners’ savings, bank loans, shares, overdrafts, trade credit, hire purchase and leasing
- explain micro-finance and crowdfunding
- distinguish between short-term and long-term finance
- match the period of finance to the purpose for which it is needed
- explain how amount required, legal form, control and existing debt affect the choice
- understand why banks may refuse to lend
- recommend and justify the most appropriate source of finance for a business.