Cash Flow Forecasting and Working Capital
This chapter explains why cash matters, how cash moves into and out of a business, how managers forecast future cash balances, and why sufficient working capital is needed for day-to-day survival.
Topic 1: Cash, Cash Flow and Profit
Cash is needed for daily payments, while cash flow shows when money actually enters and leaves the business.
1. Why Cash Is Important
A business needs cash to pay employees, suppliers, rent, taxes and other day-to-day expenses.
2. Cash Flow
Cash inflows
Amounts of money received by a business.
Cash outflows
Amounts of money paid out by a business.
3. Cash Inflows
Cash inflows are amounts of money received by a business.
- cash sales
- payments from debtors
- bank loans
- sale of assets
- money invested by owners or shareholders.
4. Cash Outflows
Cash outflows are amounts of money paid out by a business.
- buying materials
- wages and salaries
- buying non-current assets
- repaying loans
- paying suppliers or creditors.
5. Cash Flow Cycle
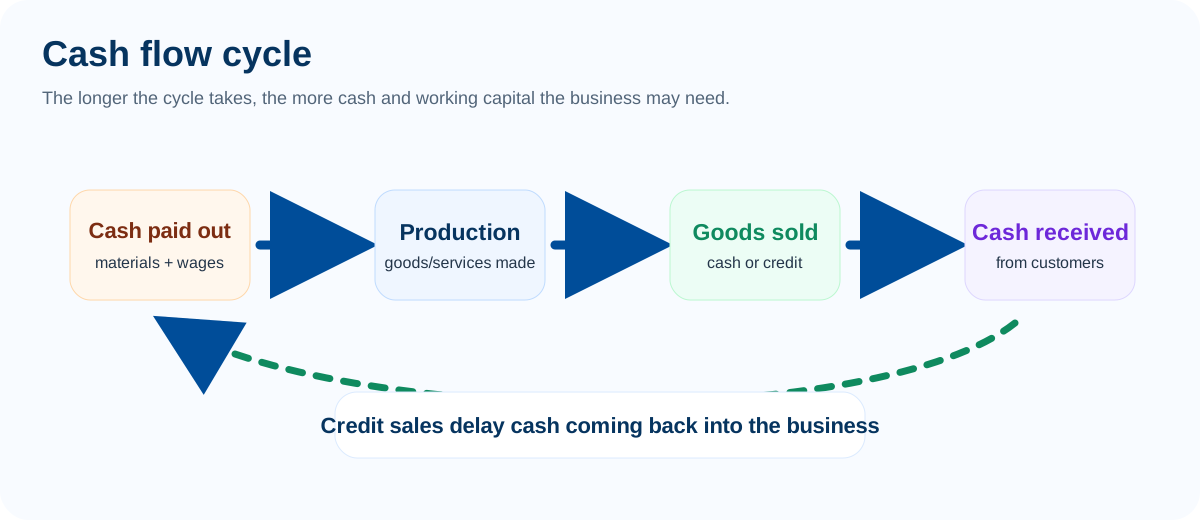
The cash flow cycle shows the stages between a business paying cash for production and receiving cash from customers.
If customers buy on credit, the business must wait longer to receive its cash. The longer this cycle takes, the more cash and working capital the business may need.
6. Cash Flow Is Not the Same as Profit
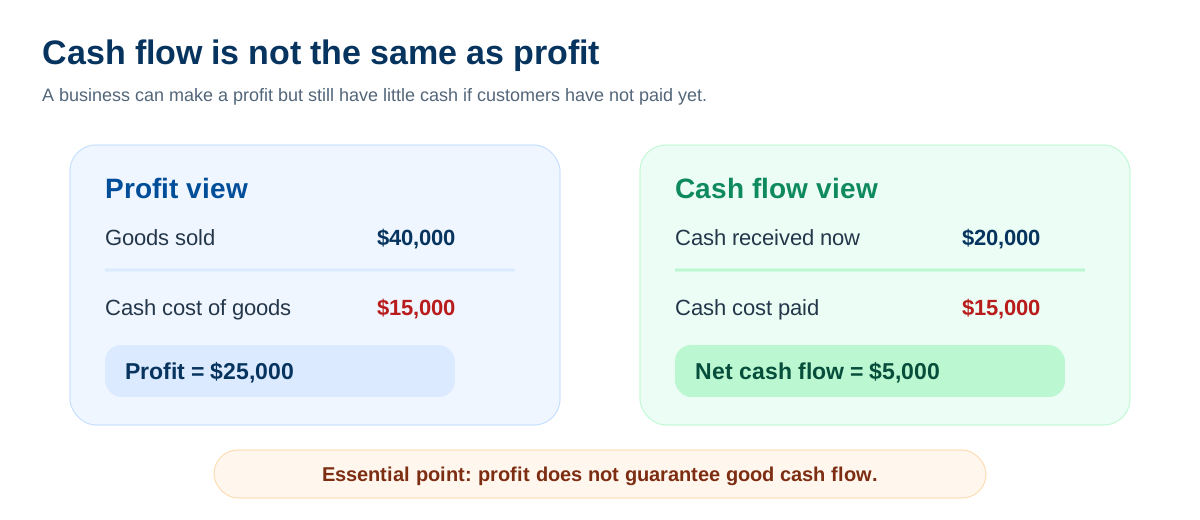
This is one of the most important points in the chapter. Profit is calculated from revenue and costs. Cash flow considers when money actually enters or leaves the business.
7. Why a Profitable Business Can Run Out of Cash
A profitable business may still experience cash shortages.
Too much customer credit
Sales may be recorded, but cash is not received immediately.
Buying too many non-current assets
Large payments for machinery, vehicles or buildings reduce cash.
Expanding too quickly
Rapid expansion may require large inventories and other spending before cash from sales is received.
Topic 2: Cash Flow Forecasts and Calculations
Cash flow forecasts help managers predict future cash balances and identify shortages before they happen.
8. Cash Flow Forecast
It is usually prepared month by month.
9. Why Cash Flow Forecasts Are Important
Cash flow forecasts help managers make better decisions before cash problems become serious.
- Predict cash shortages: Managers can identify when the bank balance may become negative.
- Arrange finance in advance: A loan or overdraft can be arranged before the shortage occurs.
- Plan business spending: Managers can see whether cash is available to buy assets or pay bills.
- Support loan applications: Banks often want to see a cash flow forecast before lending money.
10. Cash Flow Forecast Calculations
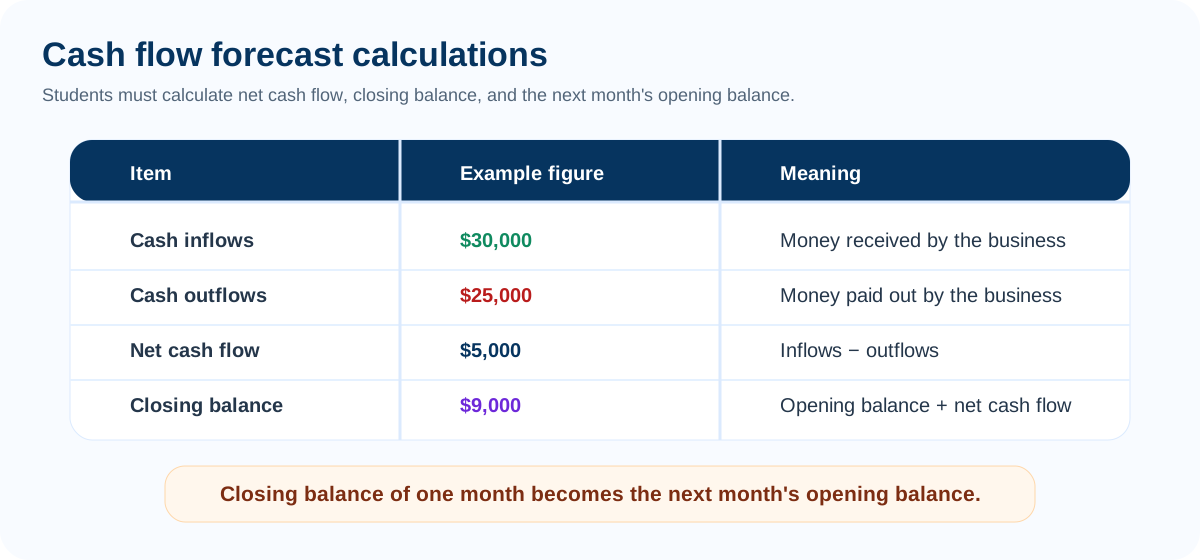
Students need to know three important calculations.
11. Example of a Cash Flow Forecast
Suppose cash inflows are $30,000, cash outflows are $25,000 and the opening balance is $4,000.
12. Positive and Negative Net Cash Flow
Positive net cash flow
Cash inflows are greater than cash outflows, so the cash balance increases.
Negative net cash flow
Cash outflows are greater than cash inflows, so the cash balance decreases.
Topic 3: Cash Flow Problems and Solutions
A business has a serious cash flow problem when it cannot meet its payments.
13. Cash Flow Problems
Possible consequences include:
- inability to pay suppliers
- inability to pay employees
- production stopping
- creditors taking action
- business closure.
14. How to Improve a Short-Term Cash Flow Problem
Four important methods are:
1. Increase bank borrowing
Advantage: immediate cash inflow.
Disadvantages: interest must be paid and the loan must eventually be repaid.
2. Delay payments to suppliers
Advantage: reduces cash outflows temporarily.
Disadvantage: suppliers may refuse further supplies or withdraw discounts.
3. Ask debtors to pay more quickly
Advantage: cash inflows arrive sooner.
Disadvantage: customers may switch to competitors offering better credit terms.
4. Delay buying capital equipment
Advantage: reduces immediate cash outflow.
Disadvantage: outdated equipment may reduce efficiency in the long run.
15. Longer-Term Solutions
If cash problems continue, a business may consider:
- attracting new investors
- reducing costs
- increasing efficiency
- developing new products to increase sales.
Topic 4: Working Capital and Exam Comparison
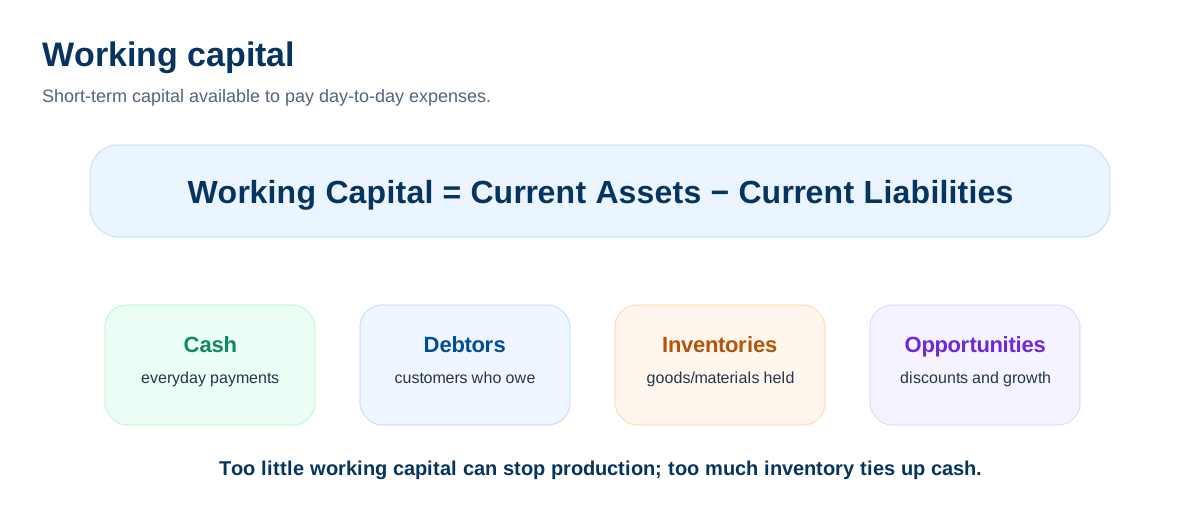
Working capital shows whether the business has enough short-term resources for daily operations.
16. Working Capital
17. Why Working Capital Is Important
A business needs enough working capital to:
- pay everyday expenses
- purchase inventories
- continue production
- take advantage of business opportunities.
18. Forms of Working Capital
Working capital may be tied up in cash, debtors and inventories.
Cash
Needed for everyday payments.
Debtors
Customers who owe the business money.
Inventories
Goods and materials held by the business.
19. Cash Flow Forecast vs Income Statement
| Cash Flow Forecast | Income Statement |
|---|---|
| Shows cash entering and leaving. | Shows revenue, costs and profit. |
| Focuses on liquidity. | Focuses on profitability. |
| Concerned with timing of cash. | Revenue may include credit sales. |
| Can forecast future balances. | Shows profit or loss for a period. |
20. Key Formulas
| Calculation | Formula |
|---|---|
| Net Cash Flow | Cash Inflows − Cash Outflows |
| Closing Balance | Opening Balance + Net Cash Flow |
| Working Capital | Current Assets − Current Liabilities |
Key Definitions
| Term | Meaning |
|---|---|
| Cash flow | Cash inflows and outflows over a period. |
| Cash inflow | Money received by the business. |
| Cash outflow | Money paid out by the business. |
| Cash flow cycle | Stages between paying for production and receiving cash from sales. |
| Cash flow forecast | Estimate of future cash inflows, outflows and balances. |
| Net cash flow | Difference between cash inflows and cash outflows. |
| Opening balance | Cash available at the beginning of a period. |
| Closing balance | Cash available at the end of a period. |
| Working capital | Short-term capital available to pay day-to-day expenses. |
What Students Must Know for the Examination
Students should be able to:
- explain why cash is important
- distinguish between cash inflows and cash outflows
- explain the cash flow cycle
- distinguish between cash flow and profit
- explain how a profitable business can still experience cash shortages
- calculate net cash flow
- calculate opening and closing cash balances
- complete and amend a cash flow forecast
- explain why cash flow forecasts are useful
- identify possible future cash shortages from a forecast
- recommend ways to solve a short-term cash flow problem
- explain advantages and disadvantages of those solutions
- define and calculate working capital
- explain why sufficient working capital is important.