Income Statements
This chapter explains why accurate accounts are important, how businesses calculate profit, how an income statement is structured, and how managers use income-statement information to support business decisions.
Topic 1: Accounts, Profit and Cash
Businesses keep records so they can measure performance and make better decisions.
1. Accounts
They record information such as:
At the end of the financial year, accountants prepare final accounts, which show the profit or loss made and the financial position of the business.
2. Why Accurate Accounts Are Important
Businesses need accurate financial records so that they can:
- calculate profit or loss
- keep track of money owed by customers
- control purchases and expenses
- calculate tax correctly
- make better financial decisions.
3. Profit
4. How Profit Can Be Increased
A business can increase profit by increasing revenue, reducing costs, or doing both.
1. Increasing Revenue
For example, the business may sell more products or increase prices where appropriate.
2. Reducing Costs
For example, the business may reduce waste or obtain cheaper supplies.
5. Why Profit Is Important
Three particularly important reasons are:
Reward for Risk Taking
Owners and investors take risks when they invest money in a business. Profit provides a reward for taking these risks.
Source of Finance
Retained profit can be kept in the business and used to finance expansion, new equipment or other investments.
Measure of Success
High profits may suggest that a business is performing successfully and can encourage investors to invest more.
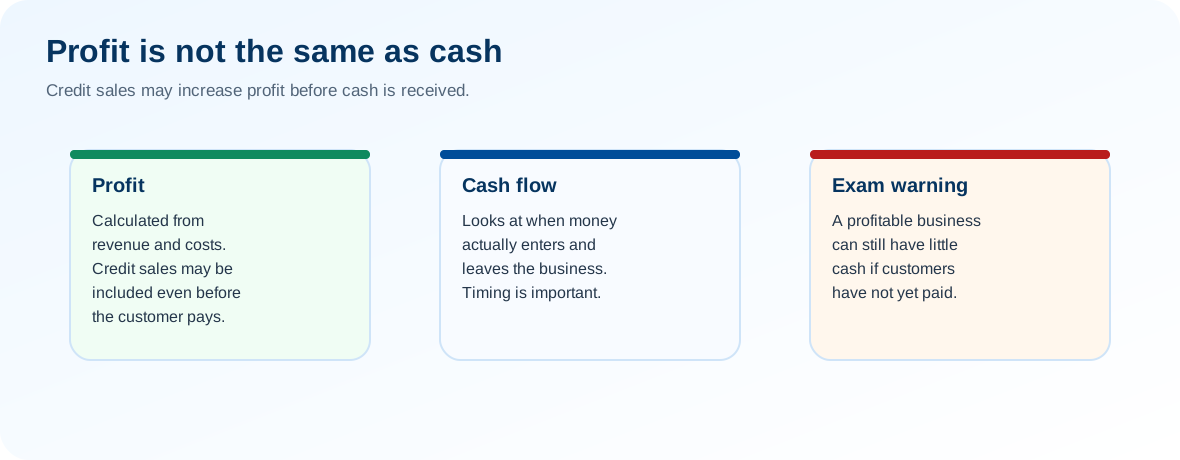
6. Profit Is Not the Same as Cash
A business can make a profit but still have very little cash. For example, goods may have been sold on credit. The sale is included when calculating profit, but the customer may not yet have paid the cash.
Topic 2: Income Statement Basics
An income statement shows revenue, costs and profit or loss over a period of time.
7. Income Statement
It is also known as a profit and loss account.
8. Revenue
9. Cost of Sales
For a manufacturer it may include materials and direct production labour. For a retailer it is mainly the cost of inventory that was sold.
10. Calculating Cost of Sales
For a retail business, cost of sales is calculated using opening inventory, purchases and closing inventory.
Topic 3: Gross Profit, Net Profit and Retained Profit
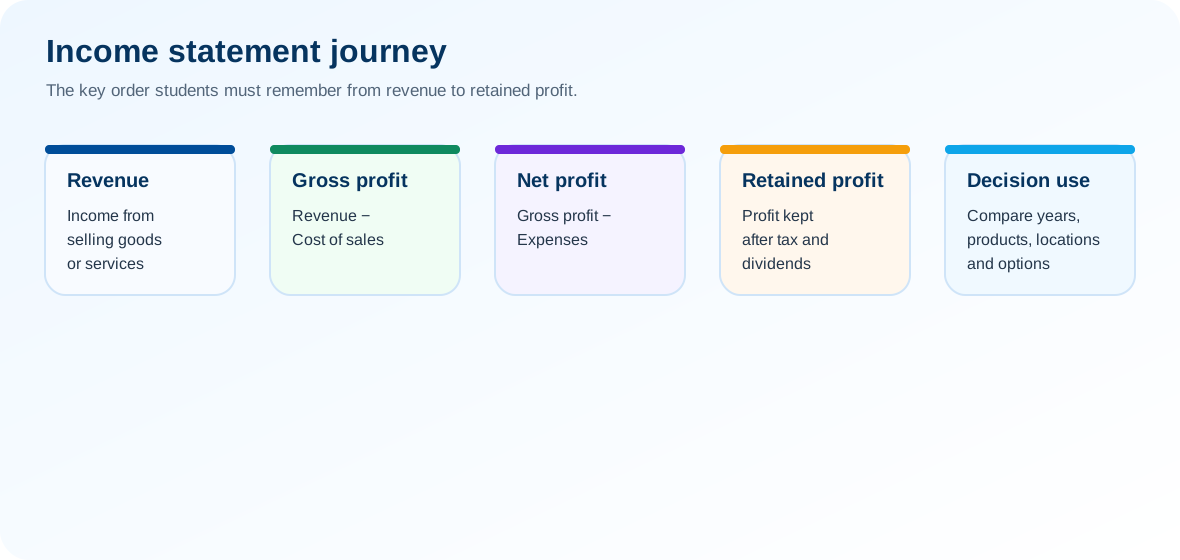
Students must clearly understand the sequence used in the income statement.
11. Gross Profit
12. Gross Profit Does Not Include All Costs
Gross profit does not deduct overhead expenses such as:
- salaries
- rent
- electricity
- advertising.
13. Net Profit
The book uses the term net profit, while noting that the Cambridge syllabus may simply call this profit.
14. Depreciation
For example, a delivery vehicle may lose value because of age and use. Depreciation is treated as an expense in the income statement.
15. Retained Profit
It can then be used to finance future business activities.
16. Gross Profit, Net Profit and Retained Profit
Students must clearly understand the difference between these three types of profit.
| Type of Profit | Calculation |
|---|---|
| Gross Profit | Revenue − Cost of sales |
| Net Profit / Profit | Gross profit − Expenses |
| Retained Profit | Net profit − Tax − Dividends |
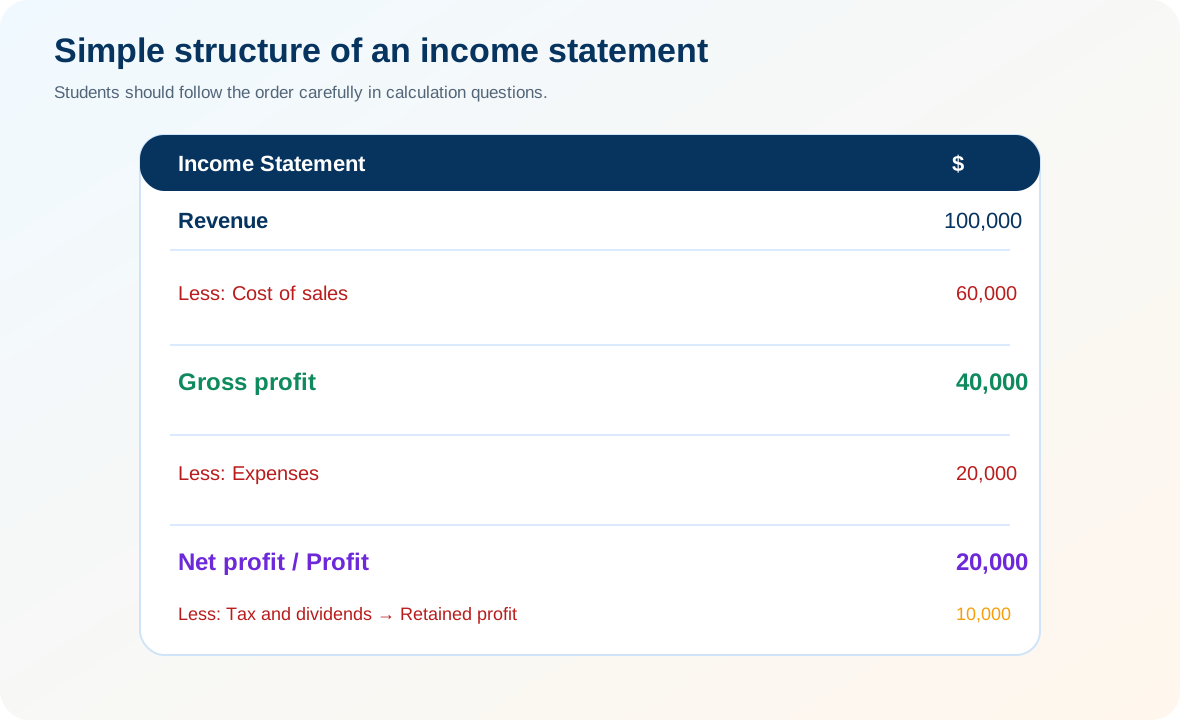
17. Simple Structure of an Income Statement
A simplified income statement looks like this:
| Income Statement | $ |
|---|---|
| Revenue | 100,000 |
| Less: Cost of sales | 60,000 |
| Gross profit | 40,000 |
| Less: Expenses | 20,000 |
| Net profit | 20,000 |
| Less: Tax | 4,000 |
| Less: Dividends | 6,000 |
| Retained profit | 10,000 |
Topic 4: Using Income Statements and Exam Calculations
Financial statements support decisions, but managers should also consider non-financial factors.
18. Using Income Statements to Make Decisions
Managers can use income statements to:
- compare profit with previous years
- compare performance with competitors
- identify why profits are increasing or falling
- compare different products
- compare alternative locations
- help decide which business option is likely to be more profitable.
19. Income Statements Do Not Make the Decision Alone
Financial information is important, but managers should also consider non-financial factors. For example, when comparing two shop locations, managers might also consider:
- future development nearby
- competition
- changes in rent
- market conditions.
20. Important Calculation Example
Suppose a business has revenue of $80,000, cost of sales of $50,000, expenses of $18,000, tax of $3,000 and dividends of $4,000.
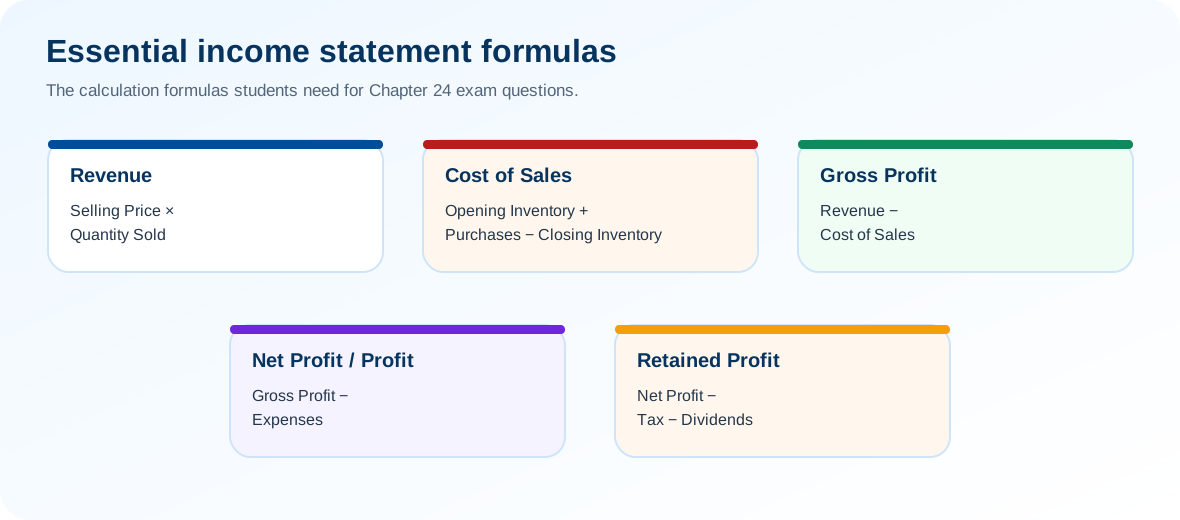
Key Formulas
| Calculation | Formula |
|---|---|
| Revenue | Selling Price × Quantity Sold |
| Cost of Sales | Opening Inventory + Purchases − Closing Inventory |
| Gross Profit | Revenue − Cost of Sales |
| Net Profit / Profit | Gross Profit − Expenses |
| Retained Profit | Net Profit − Tax − Dividends |
Key Definitions
| Term | Meaning |
|---|---|
| Accounts | Financial records of a business's transactions. |
| Income statement | Statement showing revenue, costs and profit/loss over a period. |
| Revenue | Income from selling goods or services. |
| Cost of sales | Cost of producing or buying the goods actually sold. |
| Gross profit | Revenue minus cost of sales. |
| Net profit / Profit | Profit after expenses have been deducted. |
| Depreciation | Fall in the value of a non-current asset over time. |
| Retained profit | Profit kept in the business after tax and payments to owners. |
What Students Must Know for the Examination
Students should be able to:
- explain why businesses keep accurate accounts
- explain why profit is important
- distinguish between profit and cash
- define an income statement
- calculate revenue
- calculate cost of sales
- calculate gross profit
- calculate net profit/profit
- calculate retained profit
- distinguish clearly between gross, net and retained profit
- understand the role of depreciation
- interpret a simple income statement
- compare financial results between years or business options
- use income-statement figures to support business decisions
- remember that financial information should often be considered alongside other business factors.