Statement of Financial Position
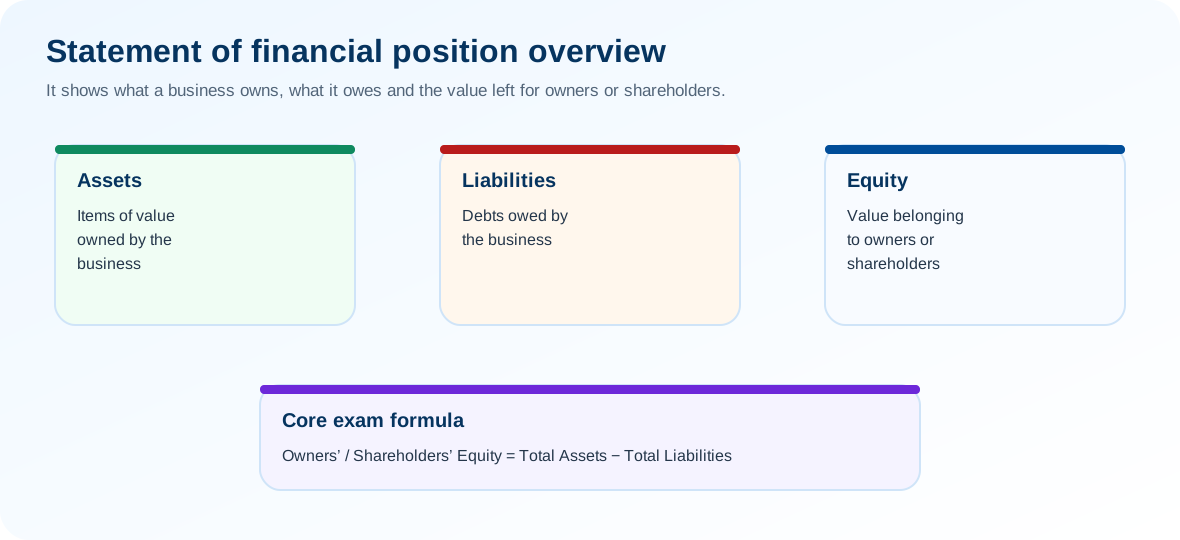
This chapter explains how a statement of financial position shows what a business owns, what it owes, and the value belonging to owners or shareholders at a particular point in time.
Topic 1: Meaning and Purpose of the Statement
The statement of financial position gives a snapshot of the business at one date.
1. Statement of Financial Position
It is usually prepared at the end of the financial year. It tells owners what the business owns, what the business owes, and how much owners’ or shareholders’ equity exists.
2. Statement of Financial Position vs Income Statement
These two financial statements are different and must not be confused.
| Income Statement | Statement of Financial Position |
|---|---|
| Shows revenue, costs and profit/loss. | Shows assets, liabilities and equity. |
| Covers a period of time. | Shows the position at one particular date. |
| Measures financial performance. | Shows the financial position or worth of the business. |
Topic 2: Assets and Liabilities
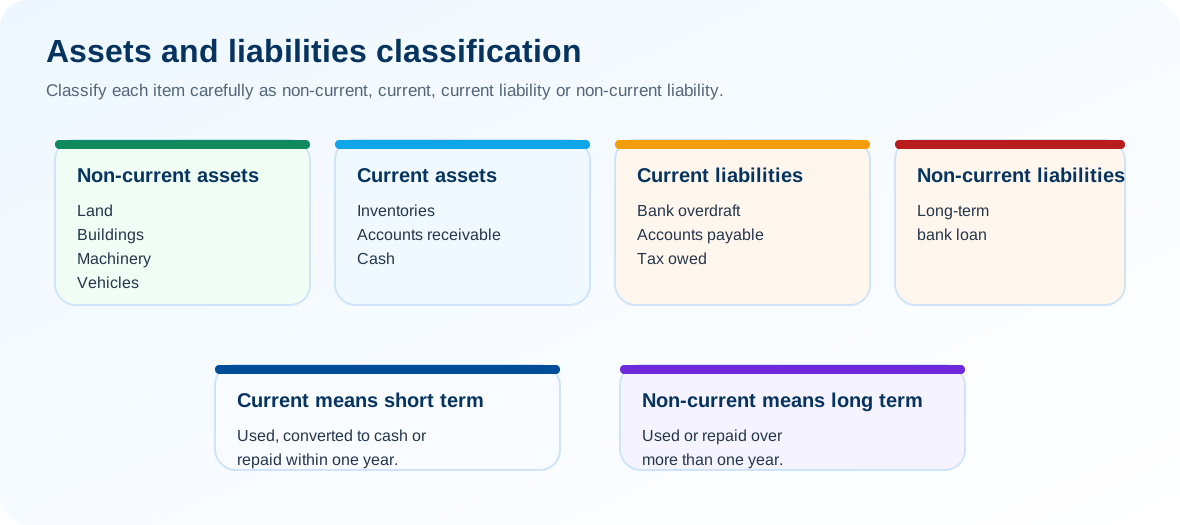
Students must classify assets and liabilities correctly in exam questions.
3. Assets
Assets are divided into non-current assets and current assets.
4. Non-current Assets
Examples include land, buildings, machinery, equipment and vehicles.
5. Intangible Assets
Some assets have value even though they do not physically exist. These are called intangible assets.
- brand names
- patents
- copyrights
6. Current Assets
Important examples are inventories, accounts receivable/debtors and cash.
7. Liabilities
Liabilities are divided into current liabilities and non-current liabilities.
8. Current Liabilities
Examples include bank overdraft, accounts payable/creditors and tax owed.
9. Non-current Liabilities
The main example is a long-term bank loan.
10. Assets and Liabilities Summary
| Category | Examples |
|---|---|
| Non-current assets | Buildings, machinery, vehicles |
| Current assets | Inventory, accounts receivable, cash |
| Current liabilities | Accounts payable, overdraft |
| Non-current liabilities | Long-term bank loan |
Topic 3: Equity, Statement Structure and Key Calculations
The statement links assets, liabilities and the value left for owners or shareholders.
11. Owners’ Equity / Shareholders’ Equity
The difference between what a business owns and what it owes belongs to its owners.
For a limited company this is often called shareholders’ equity or shareholders’ funds.
12. Shareholders’ Equity
For a limited company, shareholders’ equity mainly consists of:
Share Capital
Money invested when shareholders purchase newly issued shares.
Reserves
Profits that have been retained in the business instead of being paid out as dividends.
13. Basic Structure of a Statement of Financial Position
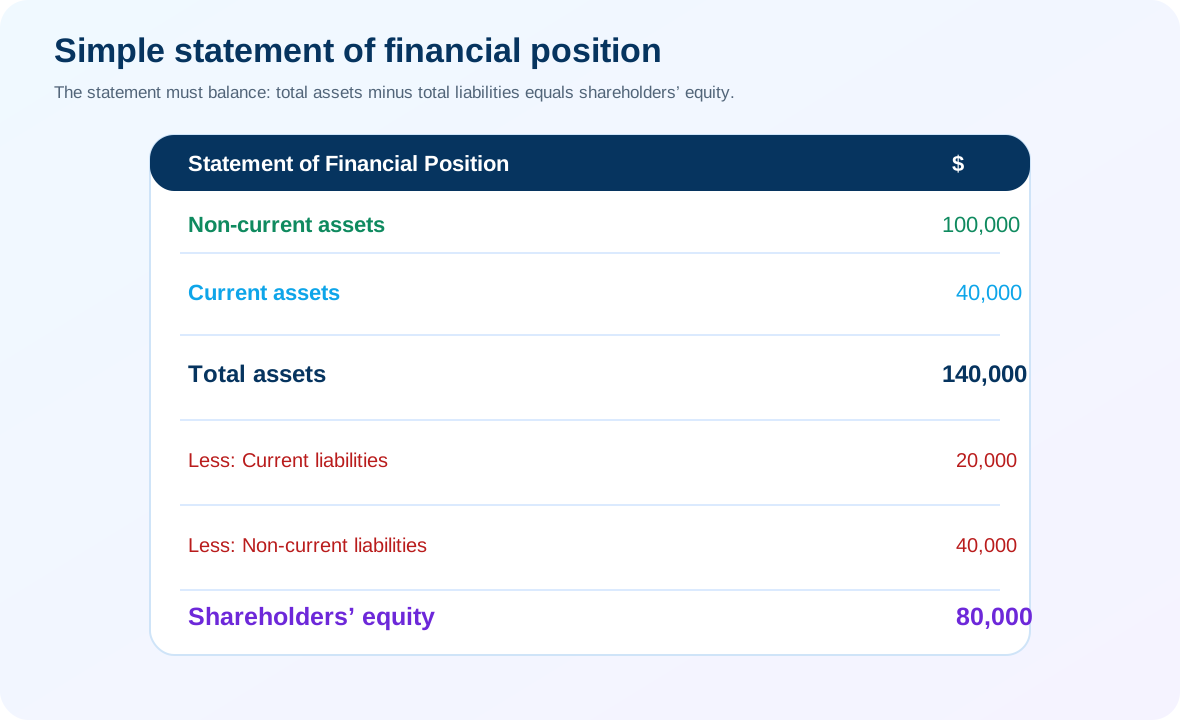
A simplified version may look like this:
| Statement of Financial Position | $ |
|---|---|
| Non-current assets | 100,000 |
| Current assets | 40,000 |
| Total assets | 140,000 |
| Current liabilities | 20,000 |
| Non-current liabilities | 40,000 |
| Total liabilities | 60,000 |
| Total assets − Total liabilities | 80,000 |
| Shareholders’ equity | 80,000 |
14. Working Capital
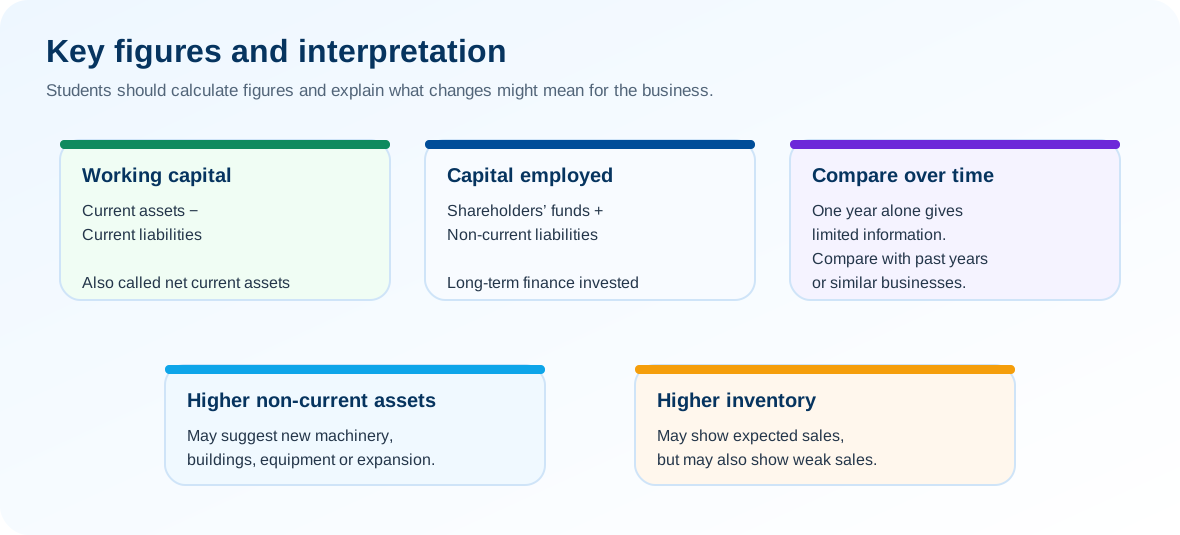
Working capital measures the short-term funds available to the business.
It is also called net current assets.
15. Why Working Capital Is Important
Working capital is needed to pay short-term debts and everyday business expenses. Too little working capital may mean the business cannot:
- pay suppliers
- pay wages
- meet other short-term obligations.
16. Working Capital Example
Current assets:
- Inventory = $20,000
- Accounts receivable = $15,000
- Cash = $5,000
17. Capital Employed
This figure becomes particularly important when calculating profitability ratios in Chapter 26.
Topic 4: Interpreting a Statement of Financial Position
In exams, calculate figures and explain what the changes may show.
18. Interpreting a Statement of Financial Position
Managers and shareholders should not just calculate figures—they should explain what changes mean. The statement can show:
- whether shareholders’ equity has increased or fallen
- whether the business has increased its long-term borrowing
- whether new shares have been issued
- whether retained profit has financed expansion
- changes in inventories
- changes in working capital.
19. Increase in Non-current Assets
If the value of non-current assets rises, the business may have purchased new machinery, bought buildings, invested in equipment or expanded production.
20. Changes in Inventories
An increase in inventory is not automatically good. It could mean the business expects higher future sales, but it could also mean products are not selling.
21. Changes in Equity
If total shareholders’ equity increases, owners may see this positively because their stake in the business has increased in value.
However, students should still look at why equity increased and whether other financial indicators have also improved.
22. Using Comparisons
One year's statement gives limited information. It becomes more useful when compared with:
- previous years
- another similar business.
23. Important Exam Application
If asked to identify assets or liabilities, choose examples appropriate to the business in the question.
Key Formulas
| Calculation | Formula |
|---|---|
| Owners’ / Shareholders’ Equity | Total Assets − Total Liabilities |
| Working Capital | Current Assets − Current Liabilities |
| Capital Employed | Shareholders’ Funds + Non-current Liabilities |
Key Definitions
| Term | Meaning |
|---|---|
| Statement of financial position | Statement showing the value of a business’s assets and liabilities at a particular time. |
| Asset | Item of value owned by the business. |
| Non-current asset | Asset owned and used for more than one year. |
| Current asset | Asset expected to be used or converted into cash within one year. |
| Liability | Debt owed by the business. |
| Current liability | Debt due within one year. |
| Non-current liability | Long-term debt repayable over more than one year. |
| Shareholders’ equity | Value belonging to shareholders after liabilities are deducted from assets. |
| Working capital | Current assets minus current liabilities. |
| Capital employed | Shareholders’ funds plus non-current liabilities. |
What Students Must Know for the Examination
Students should be able to:
- define a statement of financial position
- distinguish it from an income statement
- distinguish between assets and liabilities
- classify assets as current or non-current
- classify liabilities as current or non-current
- give suitable examples for different types of businesses
- calculate shareholders’ equity
- calculate working capital
- explain why sufficient working capital is important
- calculate capital employed
- explain how business expansion may have been financed
- interpret changes in assets, liabilities, inventories and equity
- compare statements from different years or businesses
- use the figures to make simple judgements about the financial position of a business.