Chapter 26: Analysis of Accounts
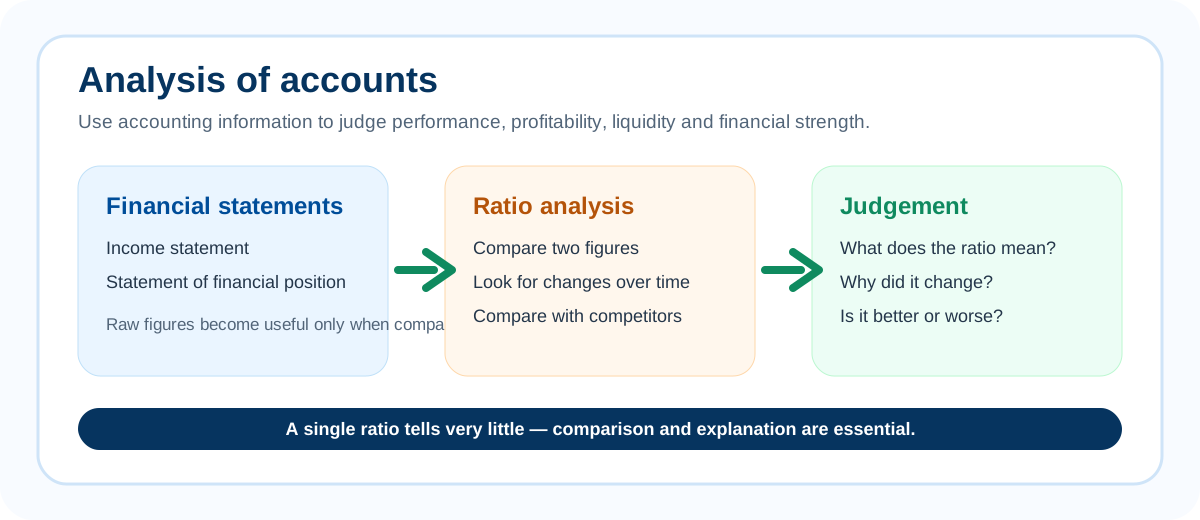
This chapter explains how students use financial statements and ratio analysis to judge business performance, profitability, liquidity and financial strength. The key skill is not only calculating ratios, but interpreting what they mean and comparing them with previous years or similar businesses.
Topic 1: Why accounts are analysed
Account figures become useful when they help users explain business performance and make comparisons.
1. Analysis of accounts
Simply knowing that one business made a higher profit than another is not enough. The larger business may also have much more capital invested, so students need to compare figures in a meaningful way.
Why ratio analysis is useful
- It helps compare the same business over different years.
- It helps compare one business with similar businesses.
- It helps users judge whether performance has improved or worsened.
2. Profit vs profitability
Profit
The amount remaining after costs have been deducted from revenue.
Profitability
Measures the profit made in relation to sales or capital invested. It is usually expressed as a percentage.
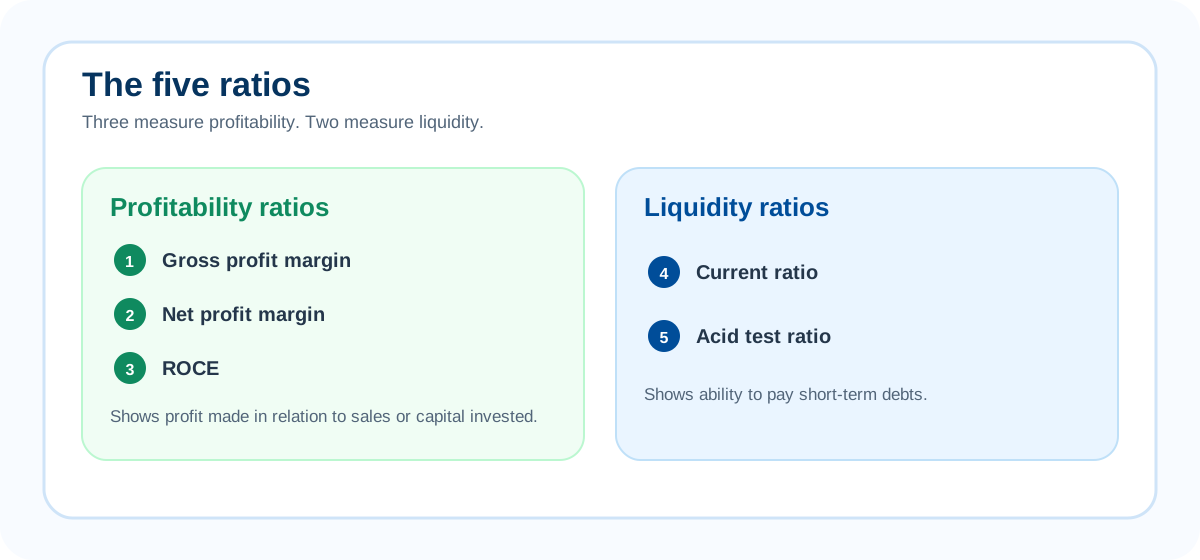
The five main ratios
| Type | Ratios students need | Main purpose |
|---|---|---|
| Profitability ratios | Gross profit margin, net profit margin, ROCE | Measure profit in relation to sales or capital invested. |
| Liquidity ratios | Current ratio, acid test ratio | Measure the ability to pay short-term debts. |
Topic 2: Profitability ratios
These ratios show how effectively the business earns profit from sales and from capital employed.
3. Return on Capital Employed — ROCE
ROCE measures how effectively the business uses the capital invested in it to generate profit.
Interpreting ROCE
- A higher ROCE generally means the business is making more effective use of its capital.
- If ROCE falls, possible reasons include lower net profit or higher capital employed.
- An increase in capital employed is not automatically bad because the business may have invested now to earn higher profits in the future.
4. Gross profit margin
The gross profit margin measures gross profit as a percentage of revenue.
What can increase the gross profit margin?
Selling prices rise
Prices may have increased by more than the cost of sales.
Cost of sales falls
The business may have found a cheaper supplier or negotiated lower purchasing costs.
5. Net profit margin
The net profit margin, also called the profit margin, measures net profit as a percentage of revenue.
Interpreting gross and net profit margins together
| Ratio | 2017 | 2018 | Possible interpretation |
|---|---|---|---|
| Gross profit margin | 20% | 24% | Improved: the business earns more gross profit from sales. |
| Net profit margin | 14% | 12% | Fallen: overhead expenses may have increased significantly. |
Topic 3: Liquidity ratios
Liquidity is about whether the business can pay short-term debts when they are due.
6. Liquidity
A business may be profitable but still experience serious liquidity problems. If it cannot pay suppliers, overdrafts and other short-term debts, creditors may eventually force it to stop trading.
7. Current ratio
The current ratio compares current assets with current liabilities. The textbook interprets this as a ratio, such as 1.25, rather than a percentage.
Interpreting the current ratio
- Around 1.5–2.0 is considered a relatively safe current ratio.
- Below 1 may indicate serious liquidity problems.
- A very high ratio, such as above 2, may mean too much money is tied up in current assets.
8. Acid test ratio
The current ratio includes inventory, but inventory may not always be easy to sell quickly. The acid test ratio removes inventory from current assets.
A result of around 1 is generally considered acceptable because the business could then just cover its short-term debts using its more liquid current assets.
| Current ratio | Acid test ratio |
|---|---|
| Includes inventory. | Excludes inventory. |
| Current assets ÷ current liabilities. | (Current assets − inventory) ÷ current liabilities. |
| Gives the general liquidity position. | Gives a stricter measure of liquidity. |
Topic 4: The five ratios at a glance
Students must be able to calculate and interpret all five ratios accurately.
9. Summary table of ratios
| Ratio | Formula | What it measures |
|---|---|---|
| Gross Profit Margin | Gross Profit ÷ Revenue × 100 | Gross profit earned from sales. |
| Net Profit Margin | Net Profit ÷ Revenue × 100 | Net profit earned from sales. |
| ROCE | Net Profit ÷ Capital Employed × 100 | Return from capital invested. |
| Current Ratio | Current Assets ÷ Current Liabilities | Ability to cover short-term debts. |
| Acid Test Ratio | (Current Assets − Inventory) ÷ Current Liabilities | Ability to cover short-term debts without relying on inventory. |
Topic 5: Users of accounts
Different stakeholders use the same accounts for different decisions.
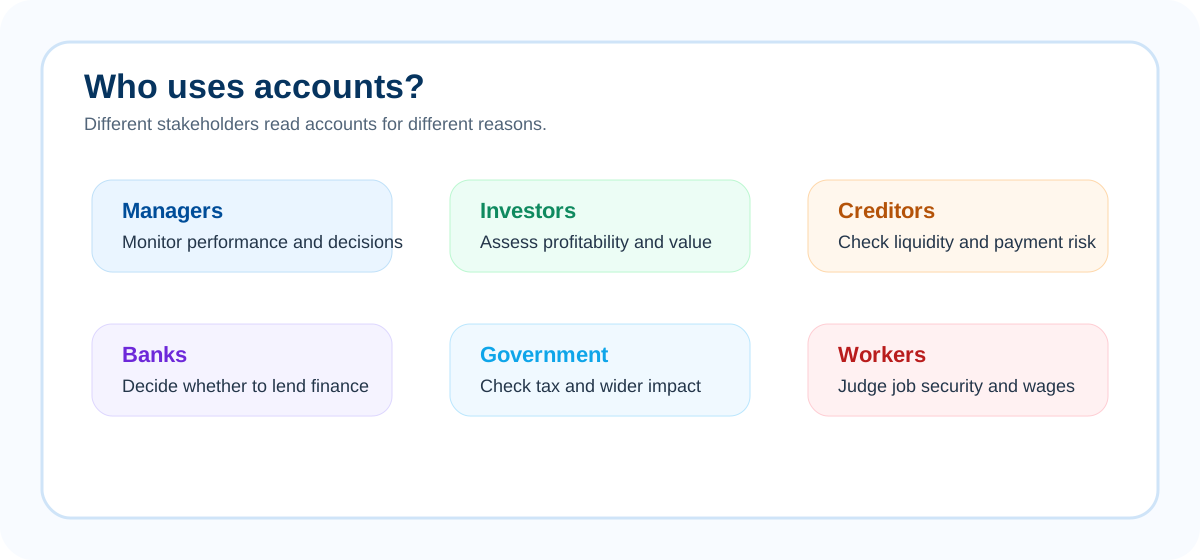
10. Stakeholders who use accounts
| User | How they use accounts |
|---|---|
| Managers | Monitor performance, identify successful and unsuccessful products or divisions, make expansion decisions, consider changing prices and decide whether to close poorly performing activities. |
| Shareholders and potential investors | Assess profitability, whether profitability is improving, whether the business's value is increasing and whether serious liquidity problems exist. |
| Creditors / suppliers | Check whether the business is likely to pay on time. Poor liquidity may cause suppliers to refuse further trade credit. |
| Banks | Analyse accounts before deciding whether to lend more money. |
| Government | Check the amount of tax due and monitor businesses whose difficulties could result in job losses. |
| Workers and trade unions | Judge whether jobs are secure and whether the business can afford higher wages. |
Topic 6: Comparisons, limitations and judgement
Good answers compare, explain and avoid relying on one number alone.
11. Why comparisons are essential
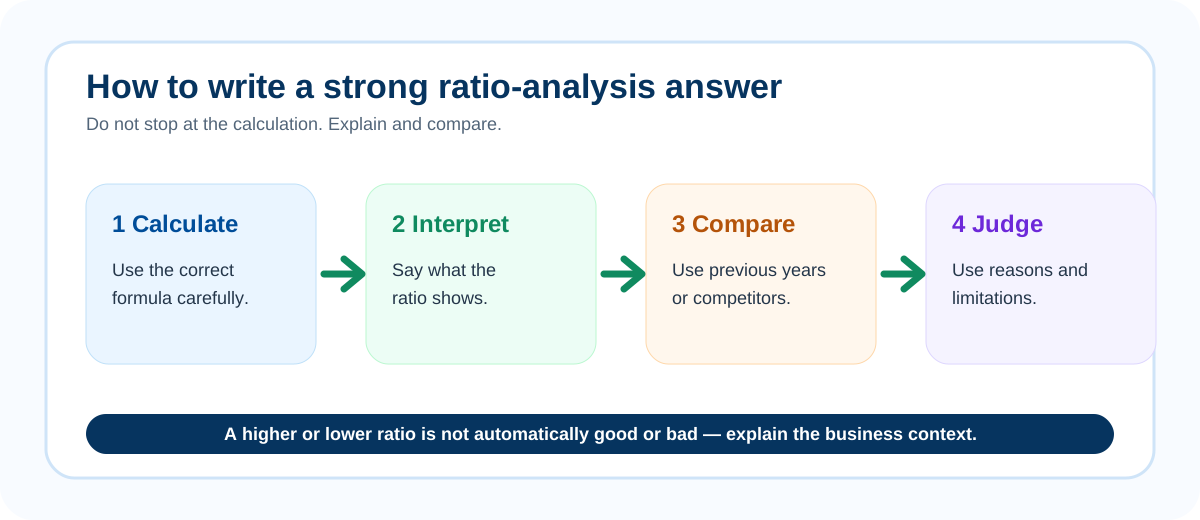
One ratio by itself has limited usefulness. For example, if a business has improved its ROCE from 5.8% to 12%, this seems positive. However, if a competitor's ROCE is 20%, the business has improved but is still less profitable than its competitor.
12. Limitations of accounts and ratio analysis
Ratio analysis is useful, but it does not provide all the answers.
Limited information
Managers have detailed internal information, but outsiders mainly depend on published accounts.
Based on the past
Past performance does not guarantee future performance.
Inflation
Rising prices may make comparisons between different years misleading.
Accounting methods
Different methods of valuing assets can make company comparisons less reliable.
13. Key definitions
| Term | Meaning |
|---|---|
| Analysis of accounts | Using accounting information to assess business performance and financial strength. |
| Ratio analysis | Comparing figures from financial statements using ratios. |
| Profitability | Profit measured relative to sales or capital invested. |
| Liquidity | Ability of a business to pay its short-term debts. |
| Capital employed | Shareholders' equity plus non-current liabilities. |
| Illiquid | Having assets that cannot easily be converted into cash. |
14. What students must know for the examination
- Distinguish between profit and profitability.
- Explain the importance of liquidity.
- Calculate and interpret gross profit margin, net profit margin, ROCE, current ratio and acid test ratio.
- Compare ratios between different years and different businesses.
- Explain possible reasons why ratios have improved or worsened.
- Understand why one ratio by itself has limited usefulness.
- Explain why managers, shareholders, creditors, banks, government and workers use accounts.
- Explain important limitations of ratio analysis.
- Use calculations to support a justified judgement about a business's financial performance.